

MD&A · 2025
In this section4 topics
Overview of Operations
Overview of Operations
Summary of Key Financial Information
The Company summarizes key financial information in following tables:
Financial position for the past 3 years, performance and cash flows for the past 2 years (Disclosure of financial performance under Financial Reporting Standard No.17)
Analysis of Financial Position (Financial statements in which the equity method is applied)
Total Assets
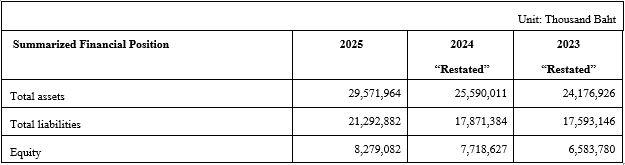
As of 31 December 2025, the Company’s total assets were Baht 29,572.0 million, increased from 2024 by Baht 3,982.0 million. Main reasons were due to an increase in reinsurance contract assets of Baht 2,897.0 million resulted from estimated reinsurance recoveries for earthquake and flood events in the southern region, corresponding to the increase in insurance contract liabilities in 2025. In the financial assets section, debt instruments and equity instruments amounted by Bath 17,619.9 million, disclosed in accordance with the requirements of Financial Reporting Standard No. 9 (Financial Instruments), compared with investments in securities, which increased by Baht 1,216.7 million or 7.4% , However, Cash and cash equivalents decreased by Baht 178.2 million due to Financial assets management policy by additionally invest in government and state enterprise securities, private sector debt instruments and Equity securities using Company’s, profits from operation for during the year. Deferred tax assets decreased by Baht 21.4 million, due to the reduction of unrealized losses arising from the measurement of investments through other comprehensive income.
Total Liabilities
As of 31 December 2025, the Company’s total liabilities increased by Baht 3,421.5 million from 2024. Main reasons were due to an increase of insurance contract liabilities of Baht 3,349.2 million, arising from reported claims resulting from the impact of earthquake and flood events in the southern region during the first and fourth quarters, respectively.
Equity
In 2025, the Company had net profit from operation of Baht 957.6 million, gain on investment in debt instrument at fair value through other comprehensive income – net of tax of Baht 172.3 million, loss on investment in equity instruments designated at fair value through other comprehensive income – net of tax of Baht 75.3 million, exchange differences on translation of financial statements in foreign currency – net of tax of Baht 2.3 million and dividend payment of Baht 472.0 million in May 2025. In addition, there was an impact from loss on remeasurements of employee benefit obligations. In overall, this resulted in an increase in equity from Baht 7,718.6 million to Baht 8,279.1 million.
Operating Results & Financial Condition
Operating Results & Profitability
Analysis of Operating Performance and Cash Flows (Financial statements in which the equity method is applied)
The Company reports its operating results for the year ended December 31, 2025, which have been audited by the external auditor in accordance with financial reporting standards. TFRS 17 was adopted in 2025, presenting financial statements under the equity method of accounting for investments.
In the year 2025, the Company recorded total insurance revenue across all product lines of Baht 19,379.8 million, increase by Baht 778.5 million or 4.2%, driven by the expansion of the Company’s general insurance business.
Insurance service expenses consist of acquisition costs related to insurance contracts under the requirements of the new financial reporting standard, and claims expenses. In the year 2025, insurance service expenses of Baht 20,405.9 million, an increasing from the previous year, The rise was mainly driven by acquisition costs related to insurance contract, marketing and sale promotion expense to expand our customer base, claims expenses increased in line with the expansion of the Company’s general insurance business, due to the earthquake in Thailand on March 28, 2025, for which the Company established claim reserves related to the event. Meanwhile, claims expenses for motor insurance increased in line with the Company’s insurance business growth in the past year, as well as the impact of flooding in the southern region during the fourth quarter of the previous year.
Net income/(expense) from reinsurance contracts held consists of reinsurance premiums ceded net of claims recoveries. In the year 2025, the Company recorded net income from reinsurance contracts held of Baht 2,208.7 million, compared to a net expense of Baht 1,492.1 million in the previous year, due to the recognition of estimated claim recoveries from reinsurance related to the earthquake event.
The Company’s annual net profit in 2025 was Baht 957.6 million, a decrease of Baht 543.7 million or 36.2% from 2024, the Company had total comprehensive income of Baht 1,033.9 million, down 27.7% from 2024 due to net profit for the year of the Company.
In response to the major natural disasters in 2025—specifically the severe earthquakes and widespread flooding in Southern Thailand—the Company has recognized the heightened risks associated with such events, as well as the critical importance of protecting its customers and policyholders. Over the years, the Company has continuously enhanced its Business Continuity Plan (BCP) by integrating stronger safety measures and regularly conducting emergency scenario simulations. These efforts aim to ensure uninterrupted operations and to minimize the impact on customers and policyholders during times of crisis.
The Company also deployed assessment teams to the affected areas to evaluate damages promptly. This proactive approach enabled the acceleration of claims processing and ensured that necessary assistance was delivered swiftly to customers and policyholders impacted by the disaster.
In terms of office infrastructure and cost management, the Company has invested in sustainability initiatives, including the installation of solar panels. This initiative reduces dependency on conventional electricity sources by generating clean, renewable energy. It not only contributes to long-term environmental preservation but also aligns with the Company’s commitment to ESG (Environmental, Social, and Governance) principles—particularly the Environmental dimension.
The shift toward solar energy has significantly lowered electricity consumption from the national grid, resulting in reduced monthly utility expenses. As energy costs continue to rise each year, this investment offers strong long-term financial benefits while reducing the Company’s environmental footprint.
Additionally, the Company continues to build an environmentally conscious organizational culture. Employees are encouraged to switch off lights during lunch breaks and turn off air-conditioning systems before the end of the workday. These practices help reduce overall energy consumption and reinforce the Company’s commitment to sustainability.
Underwriting by Class
Underwriting Information by Product is as follows:
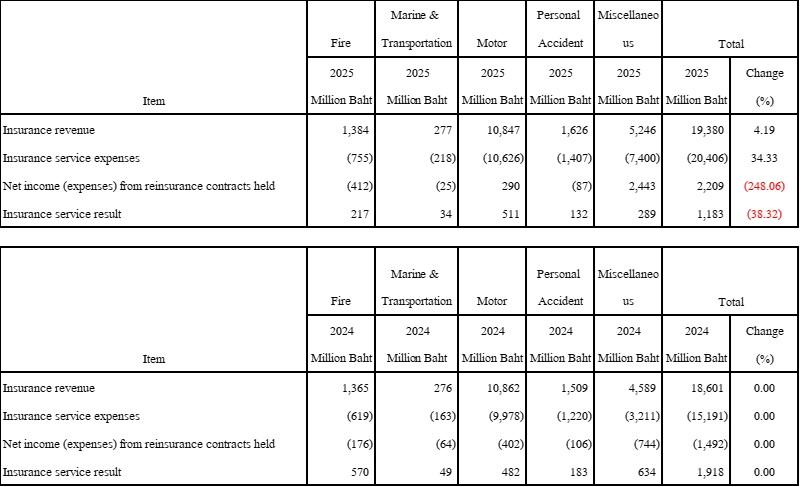
The Company had insurance revenue of fire insurance products in 2025 of Baht 1,384 million, higher than 2024 in amounting to Baht 19 million, or 1.4%. Insurance service expenses was Baht 755 million, higher than 2024 in amounting to Baht 136 million. In the year 2025, Net expenses from reinsurance contracts held was Baht 412 million. Overall, fire insurance generated insurance service result of Baht 217 million.
Marine and transportation insurance generated insurance revenue of Baht 277 million, 0.4% increasing from 2024. Insurance service expenses was Baht 218 million, increasing from 2024 by Baht 55 million or 33.7%. Net expenses from reinsurance contracts held was Baht 25 million. Insurance service result was Baht 34 million.
Motor insurance generated insurance revenue of Baht 10,847 million, decreased by 0.1%. Insurance service expenses was Baht 648 million, increased in line with higher incurred claim. In the year 2025, Net income from reinsurance contracts held was Baht 290 million, while there was a net expense from reinsurance contracts held Bath 402 million in the previous year. Overall, insurance service results increased by Baht 29 million or 6.0% from prior year.
Personal accident insurance generated insurance revenue of Baht 1,626 million, increased from previous year of Baht 117 million or 7.8%. Insurance service expenses was Baht 1,407 million, increased from prior year by Baht 187 million or 15.3%. Net expense from reinsurance contracts held decreased by Baht 19 million or 17.9% from 2024. Insurance service results for this product of Baht 132 million.
The Company had insurance revenue of miscellaneous products of Baht 5,246 million, increased from prior year. Insurance service expenses was Baht 7,400 million. Net expense from reinsurance contracts held in 2025 of Baht 2,443 million. While in the previous year there was a net expense from reinsurance contracts held of Bath 744 million. Accordingly, the insurance service result for 2025 was Baht 289 million.
Insurance service expenses
Insurance service expenses comprised amortization of insurance acquisition cash flows of Bath 5,241 million, an increase of Bath 660 million or 14.4% from the previous year due to the expansion of general insurance operations, incurred claims and other directly attributable expenses of Bath 16,998 million, an increase of Bath 4,927 million or 40.8% from the earthquake and flood events in the southern region, and changes that relate to past services - Changes in cash flows to complete the contract related to the liability for incurred claims amounting to Bath 1,833.3 million, representing an increase of Bath 372.2 million or 25.5% from 2024.
Investment
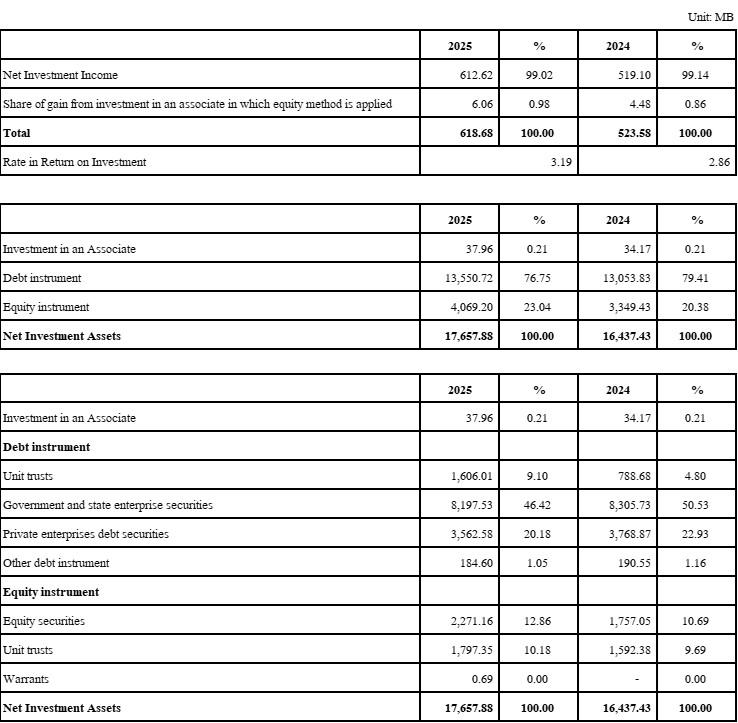
The Company had net investment income and share of gain from investment in an associate in which equity method is applied of Baht 619 million, majority from interest, dividend and gain on revaluation of financial instrument. Average return on investment was 3.19%. Details of income and investment assets classified by objectives and types are as follows:
Other operating expenses
In 2025 the Company had other operating expenses of Baht 610 million, decreased by Baht 5 million from 2024. Other operating expenses comprise of personal expenses which are not related to underwriting amounting Baht 357 million, premises and equipment expenses of Baht 100 million, and other expenses of Baht 153 million.
Income Tax
The Company’s income tax of Baht 222 million represented tax rate at 18.8% of net profit before tax. Such tax rate was lower than corporate tax per the Revenue Code. This is due to the adjustment of income tax expenses on profit before tax under Financial Reporting Standard No. 17.
Cash Flows
As of 31 December 2025, the Company had cash and cash equivalents of Baht 599 million, decreased from 2024 by Baht 178 million which made up of transactions in following activities:
Cash flows from operating activities of Baht 456 million. Cash received from operating activities consist of premium received, cash received from reinsurers, cash received on interest income, dividend income, other investment income, other income, deposits at financial institutions and cash received from financial assets of Baht 31,218 million, cash outflow from operating activities to premium paid net of ceding commissions and other directly attributable expenses, incurred claims and insurance service expenses, insurance acquisition cash flows, other operating expenses, income tax expenses and cash payments from financial assets of Baht 30,762 million.
Cash flows used in investing activities of Baht 136 million for investing in the Company’s buildings and building improvement, equipment and computer software.
Cash flows used in financing activities of Baht 497 million for dividend payment paid during the year and payment of lease liabilities.
Liquidity & Capital Adequacy
Source of Fund
Major sources of fund used in operation were derived from combination of shareholders’ equity and operating profit whereas significant portions of liabilities comprised liabilities for remaining coverage and liabilities for Incurred claims, both under insurance contracts issued and reinsurance contracts held in the normal course of insurance business.
Asset Management Capability
Quality of assets
Cash, cash equivalent, debt instruments and equity instruments
As at 31 December 2025, cash, cash equivalent, debt instruments and equity instruments were Baht 18,218.7 million, an increase of Baht 1,038.5 million or 6.0% from last year. The increase in assets was derived by the rise in financial assets.
Property, buildings and equipment, net
The net book value of property, buildings and equipment after accumulated depreciation was Baht 754.3 million. The assets decreased by Baht 33.5 million, The company disposed of assets in building improvement, fixtures and office equipment altogether with depreciation amortized during the year.
Premium receivables, net
As of 31 December 2025, the Company had net direct premium receivables of Baht 2,238.6 million. The receivables decreased by Baht 108.6 million or 4.6%.
Aging of those receivables are detailed as follows:
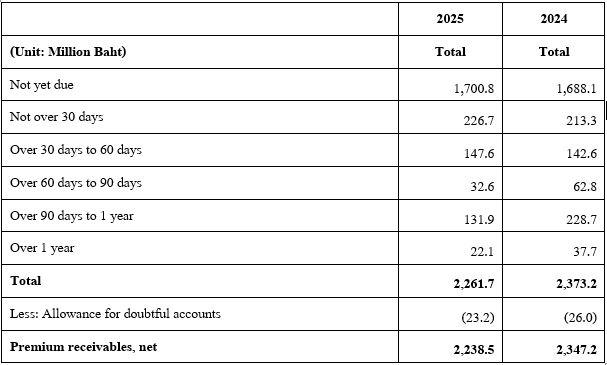
The Company assigns the Premium Management Department to manage debt collection. For outstanding debts that may incur loss on collection, the Company set up general and specific allowance for doubtful debts according to the Allowance for Doubtful Debt Policy. As of 31 December 2025, allowance for doubtful debts was Baht 23.2 million. For debtors with overdue payments, the Company set up stringent follow up process and actions such as cancellation of credit limit, obtaining letter of debt settlement agreement, pursuing proper legal action and finally reporting to relevant regulators i.e., the Thai General Insurance Association and the Office of Insurance Commission to withdraw debtors’ agent or brokerage license and etc.
Other assets
Assets with significant value held by the Company other than cash, cash equivalent, investment assets, property, buildings & equipment and reinsurance contract assets comprise of:
* Reinsurance contract assets of Baht 8,112.0 million. The assets related to reinsurance reserves to be recoverable from reinsurers to manage insurance risk which is the normal practice of non-life insurance business.
* Right of use assets, goodwill and Intangible assets of Baht 957.9 million were described in section “Operating assets” of Annual Report under Section1. Business Operation and Performance
* Deferred tax assets and other assets of Baht 1,434.6 million, increased Baht 40.7 million from previous year. Increase in other assets during the year.
Debt Obligations & Off-Balance-Sheet Management
-
Material & Related-Party Transactions
(1) Pricing policy and /or reasonableness of transactions
1) Normal commercial terms of insurance contract, price and condition setting are at the arm’s length basis for non-related persons or parties;
2) As stated in the agreement at the normal commercial terms, price and condition setting are at the arm’s length basis for non-related persons or parties
3) Dividend income is as declared;
4) Interest is charged at rates offered to other customers ranging between 0.8% to 2.4 % p.a.;
5) Claim is assessed on actual damages incurred under coverage of insurance policy at the normal course of insurance business; and/or
6) Market price of purchase and service rendered transactions, condition setting is at the arm’s length basis for non-related persons or parties.
(2) Necessity and Justification of transactions The above related party transactions have been disclosed in the notes to financial statements audited by the Auditor. The transactions were conducted to support the Company’s operations and business development with continuous and stable growth. Those transactions were in the normal course of business under market conditions with normal pricing and return. The various forms of investment such as bank deposits and shareholdings in related companies represent the Company’s investment approach in order to appropriately manage and diversify investment portfolio. In insurance business section, related transactions such as premium written, claim payment, commission and brokerage fees and other underwriting expenses have been conducted in normal business practices for the purpose of business growth. Business operations have been performed through various alliance partners. Claim transactions have been reviewed under standard claim process which is similar to the practice of claim service provided to all customers. The Company has conducted those transactions by considering the maximum benefits for the Company.
(3) Measures/Procedures for Approval of Related Party Transactions The above related party transactions and related party transactions presented in the notes to financial statements audited by the Auditor are specified to comply with the ordinary course of trade under market pricing. The conditions stated do not differ from those of the outsiders, and no stakeholders are involved in the approval of any related party transactions. Nonetheless, the Company does not have the policy to support the stakeholders to conduct related party transactions. If there will be any related party transactions, it shall be in the normal course of business with no different pricing or condition from the outsiders and will be within the notices and regulations of the Stock Exchange of Thailand, where the Audit Committee will review the suitability and the justification of such an item.
(4) Policy or Trend of Making the Related Party Transactions in the Future For the related party transactions of the Company which will take place in the future, the Company shall implement with transparency per the Good Corporate Governance of the Company and in accordance with the fair price and the market condition of the general business characteristics. Apart from that, the Company shall comply with the Securities and Exchange Act B.E. 2535 (A.D. 1992), rules, notifications, orders or requirements of the Stock Exchange of Thailand, including the compliance to the provisions concerning the disclosure of information on making the related party transactions and the procurement or sale of the important assets of the Company. Nevertheless, if there will be any related party transaction with the individual who may have the conflict of interest or the vested interest in the future, the Company shall disclose in the notes to the annual financial statements.
Debt Securities with Financial Ratio Requirements
Debt Securities with Financial Ratio Requirements Issued?
No
Factors That May Affect Financial Condition
Factors or Incidents That May Materially Affect Financial Condition
Major flood in the 3rd quarter and 4th quarter due to climate changes and water conditions in Thailand, The company has consider these factors into account and incorporate them into pricing strategies and improve future underwriting criteria to reflect risk assessments based on risks arising from climate change. Other underwriting and operating expenses came from various marketing and sales promotion expenses incurred to retain existing customers and gain new customers in high market competition. These expenses tend to increase from economic condition. In addition, insurance company needs to use information technology systems as fundamental for its operations therefore, The company has lot of expenses related to information technology systems and office building expenses. The company has implemented cost-saving measures for office buildings by installing solar panels to partially replace electricity consumption. This transition to clean energy not only helps reduce pollution in the long run but also demonstrates the company’s commitment to social and environmental responsibility. By adopting ESG (Environmental, Social, and Governance) principles, particularly in the Environmental aspect, the company aims to mitigate environmental impacts while effectively reducing office operating costs. Key measure is to lower energy expenses and office building costs. The company typically consumes significant amount of electricity for lighting, office equipment, and air conditioning systems, all of which contribute to major operational expenses. Installing solar panels allows the company to generate its own electricity from sunlight, reducing dependence on the main power grid. As a result, monthly electricity bills decrease, making this initiative a cost-effective long-term investment that alleviates financial burdens caused by rising electricity rates each year.
Projects or R&D Affecting Future Results
-